The New Zealand dollar has been range bound since the start of the week. It slipped earlier in the week, then recovered as the US dollar eased on lower yields and some moderation in oil prices.The gains, however, have been modest.Data this week has been limited to ANZ Truckometer and REINZ housing data for September. The Truckometer data showed a bounce, but the signal for grow this soft. Light traffic rose 1.1% MoM, yet was down -1.1% YoY. Annual growth in light traffic has been trending lower over the course of this year - likely as higher petrol prices have continued to weigh on NZ activity.Indeed, light traffic typically leads activity by up to six months, and given the softening in light traffic growth, it suggests momentum in growth is likely to fade through the remainder of this year as both petrol prices remain elevated and higher interest rates bite.
The heavy traffic index also rose 2.2% MoM and is up 0.7%YoY,yet annual growth has slowed from 2.6% in April. The heavy index tracks well with GDP(production) measures, and again similar with the light traffic index, it points to softer demand ahead. Turning to the REINZ data, NZ house prices fell -0.3% MoM(SA) in September, with annual price growth falling to -1%.September is usually supported by seasonal factors, and the raw index was up 0.4%, so the underlying trend is weaker than the headline suggests. Sale volumes fell -2.2% MoM and are now down -10% YoY. Indeed, it is evident that higher interest rates are likely the key driver behind the softening in the NZ housing market, with election and broader economic uncertainty likely adding to it.Looking ahead for the rest of the week, September Business NZPMI and PSI are both due on Friday. This data will provide agood read on both activity andinflation momentum ahead of Q3CPI data due next week.
The key focus this week has been on the IMF meetings in Bangkok and the subsequent release of the WEO report for October. The IMF describes the global economy asresilient but split. Growth is forecast at 3.1% this year, a touch above July, and 3.4% in 2027. Strong AI investment is propping up activity, but buffers are thinning and risks tilt to the downside. The US economy is expected to grow 2.3% this year(unchanged from the July forecast), with 2027 growth nudged up 2.3% (from 2.2%) on solid consumption and tech investment. The euro area had its growth forecast upgraded to 1.1% this year from 0.9%, with 2027 growth unchanged at 1.2%. China's growth - which has faced some challenges in recent months, particularly in its property market - was trimmed by 0.1% in both years, to 4.5% this year and 4.0% in 2027.On inflation, global headline inflation is projected at 4.7%this year, unchanged from July and driven by energy and food prices from the Middle East war, before easing to4.1% in 2027, revised up from 3.9%. Advanced economy inflation was lifted to 3.1% this year from 3.0%, and to 2.7%in 2027 from 2.4%. The US is at 3.6% this year and 2.8% in 2027, the euro area at 3.1% and 2.8%, and Japan at 2.0%and 2.6%. Core inflation is also expected to return to 2% only gradually, by mid 2028 in both the US and euro area. The IMF also expects policy to be less supportive than assumed earlier this year, with US and euro area rates expected to rise in real terms.
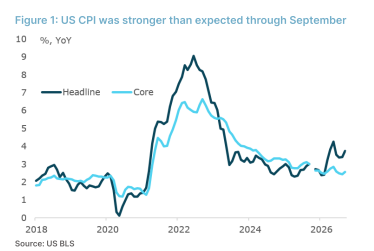
On the data front, US CPI was the focal point this week and the details leaned firmer than expected. Headline CPI rose 0.6% m/m, in line with consensus and up from 0.4%prior, which lifted the annual rate to 3.7% y/y (from 3.4%)versus the 3.6% consensus. More importantly, core inflation was also strong, rising 0.3% m/m against 0.2%expected, pushing the annual rate up to 2.6% y/y (from2.4%) and above the 2.5% consensus. The US dollar strengthened immediately after the release,likely reflecting firmer bets on Fed rate hikes. We do not expect the Fed to raise rates this month, but we suspect ahike at the final meeting in December. The Fed’s preferred measure remains PCE, but the data points to a broadening out of the inflation pressures the Fed has been flagging recently.Elsewhere, oil remained in focus. Brent rallied to its highest close since mid September on Monday hitting$108/bbl, yet prices have since steadied around $106/bbl.Houthi attacks on Saudi Arabia, including a deadly strike on Riyadh’s airport over the weekend, and Iranian attacks on tankers near Hormuz have kept risk premiums elevated. Washington added further pressures to the oil market, as President Trump announced an energy ceasefire between Russia and Ukraine and temporarily eased sanctions on Russian fuel. However, Russia has yet to confirm the truce and its refining capacity remains badly reduced, so the extra supply is likely limited.